
Mon, September 14, 2026
Stocks were broadly lower as Treasury yields reached multi-year highs. Oil rallied 8%, finishing at its highest level in nearly four months.
Economic Data
August CPI Report
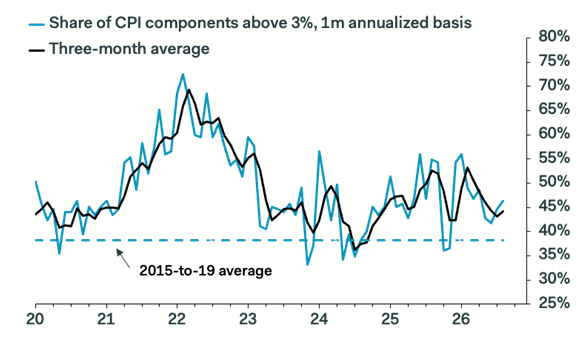
The highly anticipated August CPI report likely all but guaranteed that the Fed will raise interest rates next week. Headline CPI rose 0.4% month-over-month, matching consensus, while core CPI (ex-food and energy) rose 0.3%, slightly above expectations for a 0.2% increase. Additionally, the share of CPI components with month-over-month increases running at annualized rates above 3% ticked up to 46% from 45% in July.
Thursday's July PPI (Producer Price Index) also came in slightly hotter than expected. Based on the CPI and PPI reports, the core PCE deflator (the Fed's preferred gauge) likely rose at a 3.4% annualized rate in August, a slight uptick from July's 3.3% pace. By Friday afternoon, the probability of a 0.25% Fed rate hike at the upcoming meeting had risen to nearly 90%.
Markets
U.S. Equities
The S&P 500 snapped a four-day decline with a rally on Friday but still finished the week down 0.78%. The Russell 2000 Index of small-cap companies slid 2.38%.
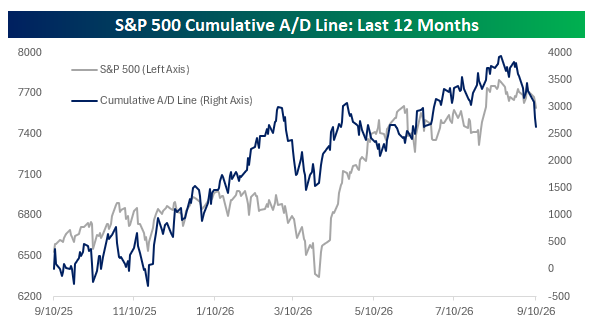
Technology and communication services were the only S&P 500 sectors to post gains. All other sectors declined at least 1.4%, continuing the recent trend of narrowing market breadth. After reaching an all-time high in August, the advance-decline line has fallen steadily.
International Equtiies
The developed-market EAFE Index fell 1.38%, while the MSCI Emerging Markets Index declined a more modest 0.23%. The European Central Bank raised its deposit facility rate by 0.25%, marking its second hike this year. The ECB remains open to further rate increases and indicated that it does not expect inflation to reach its 2% target until the end of 2027. The Bank of Japan is widely expected to raise its benchmark rate by 0.25% at its upcoming September 17-18 meeting.
Fixed Income
The 2-year Treasury yield rose to its highest level in more than two years, while the 10-year yield reached its highest level since October 2023. The 30-year yield climbed to a two-decade high. With the Fed likely to begin raising rates at its upcoming meeting, investors will turn their attention to the expected magnitude (how high rates will go) and duration (how long they will stay there) of the hiking cycle.
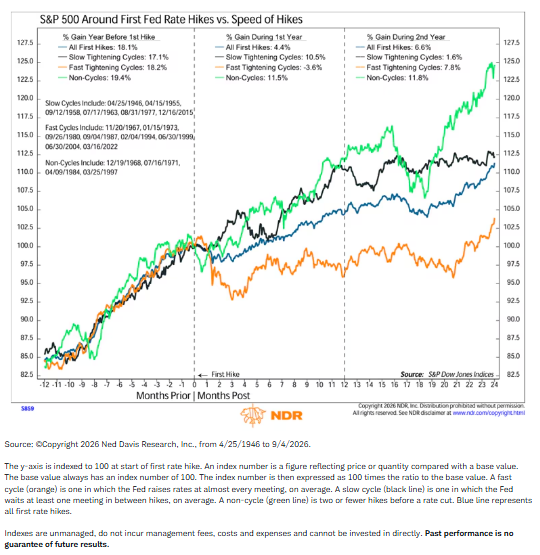
Historically, stocks have rallied ahead of the first rate hike, as is the case currently. Subsequent market performance has depended largely on the pace of tightening. Chairman Warsh's aversion to forward guidance and willingness to let markets calibrate policy create an additional layer of uncertainty.
This Week
The two-day FOMC meeting, policy decision, and Chairman Warsh's press conference will take center stage. August retail sales will be the week's most important economic data release.
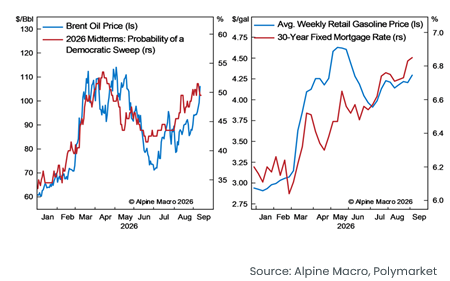
Chart of the Week
Betting market odds that the Democrats will gain control of both the House and Senate have risen to a coin flip. Betting odds have closely tracked the price of oil and gasoline.
Written By Brian Presti
--
Brian Presti, CFA®, Chartered SRI Counselor℠, is Chief Investment Officer and a shareholder at TFC Financial Management. He oversees the firm’s investment strategy, asset allocation, sustainable responsible investing, and portfolio management processes and leads the firm’s Investment Committee. Prior to joining TFC in 2023, Brian was Director of Portfolio Strategy at The Colony Group, Chief Investment Officer of Harvest Capital Management and an equity analyst and portfolio manager with DL Carlson Investment Group. He began his career in 1997. As CIO, he is responsible for evaluating investment managers and implementing portfolio strategies designed to support long-term client objectives.